
How to Get Out of Debt With These 5 Tips
If you have ever wondered how to get out of debt without giving up every small joy in your life, you are in the right place. A few years ago, my husband and I sat at our kitchen table, opened every statement we had been avoiding, and added everything up. Credit cards, a car loan, student loans, a couple of medical bills we had been pretending did not exist. The total made my stomach drop.
But here is the part I want you to hear first: we did not stay stuck. We built a simple plan, followed it month after month, and knocked out more than $50,000 of that debt in under a year. We kept traveling, we kept our date nights, and nobody had to survive on rice and beans. Getting out of debt does not have to be miserable. It just has to be intentional.
In this guide, I am walking you through the exact 5 steps we used, in the order we used them. These are the same steps I recommend to anyone who asks me how to get out of debt, whether they owe $5,000 or $150,000. Grab a notebook, pour some coffee, and let us map your way out together.

Step 1: List Every Debt You Owe, Smallest to Largest
The very first move in learning how to get out of debt is facing the numbers. Not roughly. Exactly. Sit down with your partner if you have one, open every account, and write down each debt with its balance, interest rate, and minimum payment. Credit cards, store cards, car loans, medical bills, personal loans, student loans. Everything except your mortgage goes on the list.
Then sort the list from the smallest balance to the largest balance. This order matters more than you think, and I will explain why in Step 4. For now, just get it all on paper. When we did this, seeing every number in one place was honestly terrifying. I almost closed the notebook and walked away.
Do not do that. The number is just a starting line, not a life sentence. Once it is written down, it stops being a vague cloud of anxiety and becomes a concrete problem you can solve. And a concrete problem can be attacked one piece at a time. Give yourself ten minutes, be brutally honest, and finish the list.

Step 2: Build a Zero-Based Budget That Tells Every Dollar Where to Go
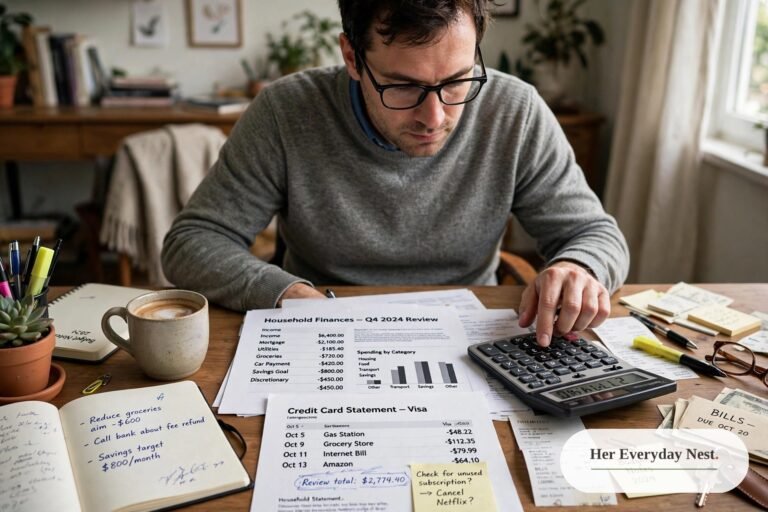
A budget is the roadmap for your entire debt payoff journey. Without one, extra money leaks out through takeout, subscriptions, and impulse buys, and you end the month wondering where it all went. With one, every dollar gets a job before the month even starts.
The method we use is called a zero-based budget. It is beautifully simple: take your monthly take-home pay, subtract every planned expense, and aim for the difference to be zero. Income minus expenses equals zero, because every dollar has been assigned somewhere on purpose. Savings counts as an assignment too, so it is not spending, it is directing.
Your first budget will not be perfect. Ours was a mess. Unexpected expenses popped up, we forgot categories, and we overspent on groceries twice. That is normal. Adjust the plan mid-month and try again next month. The magic is not in a perfect spreadsheet. The magic is in doing it every single month, because budgeting is how you discover the extra money that will crush your debt. If you are brand new to budgeting, my guide on how to budget your money for beginners walks you through your very first one.

Step 3: Save a Small Emergency Fund Before You Attack the Debt
This step surprises people, but it is the one that keeps your whole plan from collapsing. Before you throw every spare dollar at your debts, park a small emergency cushion in a separate savings account. Start with $1,000, or one month of essential expenses if you can stretch to it.
Why? Because life does not pause while you pay off debt. The car needs new brakes. The kid needs stitches. The water heater picks the worst possible week to die. Without a cushion, every surprise goes straight back onto a credit card, and you are right back where you started, discouraged and deeper in the hole.
Think of the emergency fund as a firewall between your progress and bad luck. Save 50 percent of your budget surplus toward it until it is funded, then redirect the full surplus to debt. It slows the debt payoff by a month or two at the start, and it saves the entire journey a dozen times over. For a deeper walkthrough, read 5 tips to build your emergency fund fast.

Step 4: Attack Your Debts One at a Time With the Snowball Method
Now the fun part. You have your list sorted smallest to largest from Step 1, and you know your monthly surplus from Step 2. Here is how to get out of debt faster than you think: pay minimums on everything, then throw every extra dollar at the smallest balance. When that one is gone, roll its entire payment into the next smallest. The payment snowballs bigger with every debt you kill.
Mathematically, paying the highest interest rate first saves a little more money. Psychologically, the snowball wins, and psychology is what finishes a two-year journey. Every time a balance hits zero, you get a burst of proof that this is working. That proof is fuel. We paid off our tiniest medical bill first, a couple hundred dollars, and I swear we celebrated like we had won the lottery. Two months later, that victory was still pushing us.
One rule: do not add new debt while the snowball rolls. Put the credit cards in a drawer, delete the saved card numbers from your shopping apps, and unsubscribe from the store emails that tempt you. If you want the full breakdown of why this method works, check out does the debt snowball method really work.

Step 5: Find Extra Money Every Month by Spending Less and Earning More
Your budget gave you a surplus, and the snowball needs fuel, so Step 5 is all about widening the gap between what comes in and what goes out. Attack it from both sides at once.
On the spending side, go line by line through three months of bank statements and circle everything that did not make your life meaningfully better. Cancel the subscriptions you forgot about, call your insurance and phone providers and ask for a lower rate, meal plan for two weeks straight, and put yourself on a 30-day pause for non-essential purchases. Most households find a few hundred dollars a month hiding in plain sight.
On the earning side, even a small side income supercharges the snowball. Sell the stuff cluttering your closets, pick up weekend shifts, freelance a skill you already have, or try a few of the ideas in my post on easy ways to make extra money every month. An extra $300 a month is $3,600 a year aimed directly at your smallest debt. That is not small money. That is a paid-off car loan.
Keep Your Motivation Alive for the Whole Journey
Knowing how to get out of debt is one thing. Staying with it for 12, 18, or 24 months is another. Motivation fades, so build systems that keep it alive. Write down exactly why you want to be debt free and put it where you will see it every day. Ours was taped to the bathroom mirror: freedom, options, and never arguing about money again.
Track your progress visually. Color in a debt thermometer on the fridge, keep a running total in your phone notes, or update a simple chart every payday. Watching the total shrink is addictive in the best way. And find your people. An online debt-free community, a friend on the same journey, or even just one person who cheers your wins will carry you through the months when it feels slow.
Finally, plan for the wobbles. You will have a bad month. An emergency will eat your surplus, or you will overspend on a vacation and feel guilty. That is not failure, that is life. The only way to actually fail is to quit. Just start the next month fresh and keep rolling.

The Bottom Line
Learning how to get out of debt comes down to five moves: list every debt, budget every dollar, build a small emergency cushion, snowball your payments from smallest to largest, and widen the gap by spending less and earning more. None of them are complicated. All of them work. The couples and families who become debt free are not the ones with the highest incomes. They are the ones who started, stayed consistent, and refused to quit.
Your turn starts today. Open that notebook, write the list, and take Step 1. A year from now, you will be so glad you did.
Frequently Asked Questions
How long does it take to get out of debt?
It depends on how much you owe and how much extra you can pay each month, but most households following the 5 steps above see major progress within 12 to 24 months. The debt snowball method speeds things up because every paid-off balance frees more money for the next one.
Should I pay off debt or save money first?
Do both in order: first save a small starter emergency fund of $1,000 or one month of expenses, then throw everything extra at debt. The cushion prevents new debt when surprises hit, which is why learning how to get out of debt starts with the emergency fund step.
What is the fastest way to get out of debt?
The fastest realistic way is combining a zero-based budget with the debt snowball method and adding extra income. Paying minimums on everything while attacking the smallest balance first, plus an extra few hundred dollars a month from cutting spending or side income, can cut years off your payoff timeline.
Is it better to pay off the smallest debt or the highest interest debt first?
Paying the highest interest rate first saves the most money on paper, but paying the smallest balance first, the snowball method, wins on motivation. Quick wins keep you going, and finishing the journey matters more than optimizing it.
Can I get out of debt on a low income?
Yes. The steps work at any income because they are about directing money intentionally. On a lower income, focus extra energy on cutting expenses ruthlessly and adding even a small side income makes an outsized difference to your payoff speed.
Emily Carter is the founder and editor of Her Everyday Nest. After nine years of renting in five apartments across three cities, she's learned how to make any rental feel like home.